Robot and Laser Market Data: What the Latest Figures Mean for Welding Automation
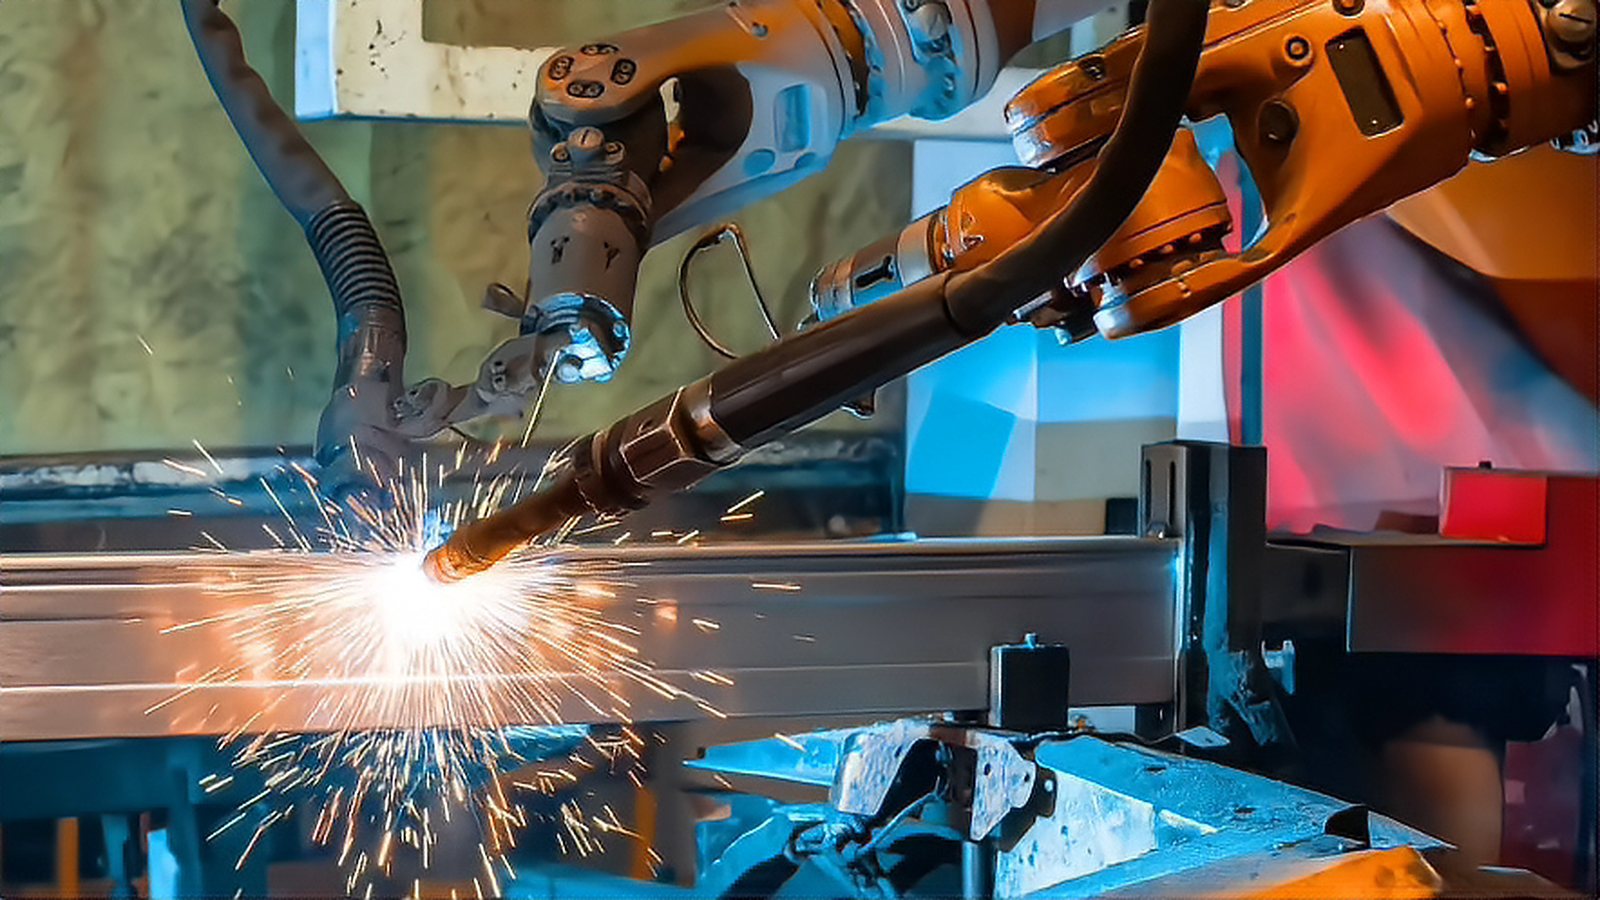
Welding automation does not exist in a vacuum, and the numbers that describe the wider robot and laser market are a practical input for anyone specifying a cell, a cobot, or a laser source. Suppliers quote market growth to justify lead times and price changes, and procurement teams quote the same figures back at them. The difficulty is that much of the market data circulating online cannot be traced to a primary source, which makes it risky to use in a capital request or a supplier negotiation. This article relies on two families of verifiable data only: the International Federation of Robotics (IFR) World Robotics reports, and the laser processing figures published by Optech Consulting. Where the public evidence stops, this article says so plainly.
For welding engineers, integrators, maintenance and quality teams, and buyers, the useful output of this data is directional rather than predictive. The figures show which regions are adding robot capacity, whether the installed base is expanding, and which downstream industries are driving installations. That directional read is enough to sanity-check a capex plan and to test a supplier's claims, even without a welding-specific breakdown, which the public data does not provide. If you are early in planning, our overview of automation systems is a sensible starting point.
Why Welding Automation Teams Should Care About This
Two numbers explain the relevance immediately. The global operational stock of industrial robots now exceeds five million units, and annual installations are running above 600,000 units. Every robot added to that stock creates demand for integration, tooling, fixtures, consumables, and service, and a meaningful fraction of that ecosystem is welding-related. When the installed base grows, the aftermarket for welding consumables, torch parts, and wire feeders grows with it. Watching these figures is a way to anticipate the commercial conditions you will face.
What the Latest IFR Figures Show
The IFR released World Robotics 2026 on 24 September 2026, covering 2025 data. The global operational stock of industrial robots passed five million units, an increase of about nine percent year on year. Annual installations in 2025 exceeded 600,000 units, up about eleven percent. Looking forward, the IFR forecasts roughly nine percent growth in 2026, to 655,000 units, and projects 806,000 units by 2029.
The previous edition, World Robotics 2025, published on 25 September 2025 and covering 2024, provides the baseline. Global installations in 2024 were 542,076 units, down about two percent from the record 552,946 units installed in 2022, but still the second-highest total on record. The 2024 operational stock stood at 4,663,698 units, up nine percent. Read together, the two editions describe a market that slipped slightly in 2024 and then reaccelerated in 2025. That matters for welding because the installed base, not the annual figure alone, determines the service and consumables market that supports a cell over its life.
The Regional Picture and China's Share
The regional split for 2024 was 401,665 installations in Asia, up five percent and equal to 74 percent of the world total; 85,006 in Europe, down eight percent and 16 percent; and 50,077 in the Americas, down ten percent and nine percent. China installed 295,045 units in 2024, a 54 percent share of global installations and a record, and its operational stock reached 2,027,190 units, 43 percent of the global base. Other 2024 country figures included Japan at 44,453 units, the United States at 34,164, down nine percent and 68 percent of the Americas total, Korea at 30,596, Germany at 26,982, Italy at 8,783, Mexico at 5,594, Spain at 5,086, France at 4,900, and Canada at 3,787.
The 2026 edition shows that shift continuing. China installed 354,000 units in 2025, up 20 percent, which is 59 percent of global installations. Domestic Chinese manufacturers supplied 195,000 of those units, giving them a 55 percent share of their home market. The United States installed about 38,500 units in 2025, up 12 percent, overtaking Japan to become the world's second-largest market. For a welding integrator or a buyer sourcing equipment, the practical reading is that incremental volume and the most intense price competition are increasingly concentrated in China, while the Americas and Europe show more modest and uneven growth. If your work centers on robotic welding cells, that regional concentration has direct implications for where components are made and where integrator capacity is expanding.
Industry Mix and the Welding Data Gap
The 2024 edition also breaks installations down by industry. Electronics was the largest sector at 24 percent, automotive followed at 23 percent, and metal and machinery accounted for 16 percent. These three sectors all use welding heavily, so their combined weight, close to two-thirds of installations, is a reasonable indirect signal that general robot demand is a workable proxy for welding automation demand. Here, however, the public data runs out.
This is the most important caveat in this article. The IFR press releases and executive summaries do not publish a figure for welding's share of robot installations. That split exists only in the paid full report. Numbers that circulate online, such as welding accounting for fifteen percent, twenty-two percent, or fifteen point five percent of installations, contradict one another and cannot be traced back to an original IFR page. We therefore do not repeat any of them here.
The honest position is straightforward. Public data supports statements about total robot volumes, the installed base, and regional and industry distribution. It does not support a welding-specific share. That gap is itself a conclusion, not a footnote. If a supplier presents a welding-share percentage and attributes it to the IFR, ask which page of which report it appears on. If the answer is vague, treat the number as unreliable, and do not let it anchor a business case. Use the verifiable industry distribution instead, and accept that the welding-specific share remains unknown rather than substituting a convenient but unsourceable figure.
What the Laser Figures Do and Do Not Mean
Laser processing data demands equal discipline, for a different reason. The same market is frequently described using two different measurement boundaries, and the resulting figures can confuse a project estimate. Optech Consulting, a German laser and photonics consultancy with a transparent methodology, separates the two boundaries explicitly. The first is laser material processing systems, which includes system integration and reflects equipment or machine-tool revenue. That market was 23.5 billion US dollars in 2023, 22.5 billion in 2024, a decline of four percent, and 24.0 billion in 2025, described as a record high with growth of roughly five to seven percent and given as a preliminary figure in January 2026.
The second boundary is lasers used for processing, which reflects spending on light sources and components and is much smaller. That figure was 5.4 billion US dollars in 2023 and 5.0 billion in 2024, a decline of 7.5 percent. Confusing the systems boundary with the source boundary is a common cause of inflated claims, because the two differ by roughly a factor of four. When someone quotes a laser market number, the first question should be which boundary it uses. Our overview of laser welding categories can help frame the equipment decision, but the boundary is what makes a headline number comparable.
Optech attributes the 2024 decline specifically to reduced high-power cutting systems and reduced high-power welding systems, the latter driven by falling demand in electric-vehicle related applications. Micromachining, by contrast, grew on the strength of recovery in semiconductors, panels, and circuit boards. The electric-vehicle driven pullback in high-power welding is a directly relevant signal for anyone building laser cells for battery production. It suggests that capacity added during the EV buildout was sufficient to absorb demand for a period, and that purchases of new high-power welding systems slowed in 2024 even as other laser segments expanded. Teams planning a battery-pack cell should weigh that context, and our notes on laser welding copper and aluminum for EV battery packs cover the process side of that decision. This article deliberately does not quote any market size figure for laser welding equipment specifically, because such numbers circulate widely and differ by an order of magnitude or more.
Forecasts Get Revised So Do Not Fix on Them
Forecasts deserve particular caution. In 2025, the IFR projected that global installations would grow six percent during 2025, to 575,000 units. The actual 2025 figure came in above that projection. In other words, the IFR's own annual forecast was revised upward by the time the next edition appeared. This is not a criticism of the IFR; it is a reminder that any single forecast number is a point estimate that will move. The projections of 655,000 units for 2026 and 806,000 units for 2029 should be read the same way. Treat forecasts as directional ranges, stress-test plans against outcomes several percentage points on either side, and revisit the numbers each year rather than locking a business case to one figure. The same logic applies on the laser side, where the 2025 figure of 24.0 billion dollars was described as preliminary, and preliminary values are subject to revision.
What This Means for Engineers and Buyers
First, use the robot data directionally. The installed base passing five million units and the 2025 rebound indicate that automation demand is expanding, which supports investment in capability, but they say nothing specific about welding. Do not let a general growth figure stand in for a welding-specific business case.
Second, treat any welding-share statistic with suspicion. Ask for the primary source every time. If it cannot be produced from the IFR reports, do not place it in a capex document or a supplier comparison, because an unsourceable number can undermine the credibility of the rest of your analysis.
Third, be precise about laser market boundaries. When comparing quotes or sizing a project, state whether a figure refers to systems and integration or to the laser source alone, since the two differ by roughly a factor of four. A number quoted without its boundary is not comparable to anything.
Fourth, plan around forecast revision and lean on structured guidance. Sizing a cell, choosing a cobot versus a robot, and laying out floor space are engineering decisions informed by data but not determined by it. Our buyer guides collect the practical criteria, and the checklist for how to specify a laser welding cell is a useful starting template. No public dataset replaces a welding-specific one, because none exists at the granularity people often want. What the public data gives you is a reliable read on overall robot and laser demand, a clear view of where that demand is concentrated, and an honest boundary around what remains unknown. Those three things are more useful than a precise-looking number that no one can source.
Sources and references
- IFR World Robotics 2026 press release - Global robot stock passed five million units, 2025 installations exceeded 600,000 units, and the 2026 and 2029 forecasts. View source
- IFR World Robotics 2025 press release - 2024 installations of 542,076 units, operational stock of 4,663,698 units, and regional totals. View source
- IFR World Robotics 2025 Executive Summary - Industry distribution and country-level installation data for 2024. View source
- Optech Consulting laser market data - Laser material processing systems and lasers for processing, including the 2024 decline drivers. View source
Comments (0)
No comments yet.
Sign in to join the discussion.